Explore the Myrtle Beach Real Estate Blog

Find exactly what you need, whether you're buying, selling, or just getting to know the Grand Strand.

01

Buying a Home

First-time buyer guides, financing tips, and how to win in the Myrtle Beach market.

02

Selling a Home

Pricing, staging, and the marketing that actually gets coastal homes sold.

03

Lifestyle and Communities

Coastal living, local communities, and what day-to-day life is really like along the Grand Strand.

04

Market Updates

The latest on prices, inventory, and what it means for you.

05

Moving & Relocation

Relocating to the coast? Tips on the move, schools, and settling into the Grand Strand.

06

Offer to Close

Step-by-step guides to buying and selling on the Grand Strand — from your first offer through closing day.

Oct. 21, 2026

Final Walk-Through Before Closing: What to Check in Myrtle Beach

The final walk-through is your last look at the house before it becomes yours. It's not a second inspection. It's a check that the home is in the shape you agreed to buy it in, and that nothing changed since you went under contract.

Most walk-throughs happen within a day or so of closing. Plan on 30 to 60 minutes. Bring your agent, your phone, and a copy of any repair agreement you signed with the seller.

What the Walk-Through Is Really For

You're confirming three things. The agreed repairs got done. Nothing new got damaged. And everything that's supposed to stay with the house is still there.

Moving out is rough on a home. Furniture scrapes walls. Movers bump door frames. A storm can roll through between inspection and closing. The walk-through is how you catch those issues while you still have leverage to fix them.

Check the Repairs You Negotiated

Pull out your repair addendum and go line by line. Ask for receipts or invoices from the contractors who did the work. If the seller agreed to have the roof patched, look at the ceiling below it. If they agreed to service the heating and air, check for a service tag or paperwork. "Done" should mean done by the standard in your contract, not a quick fix that hides the problem.

Test the Systems Room by Room

Turn things on. Run the heat and the air for a few minutes each. Flip every light switch. Run water in every sink, tub, and shower, and flush every toilet. Look under the sinks for drips while the water runs.

In the kitchen, run the dishwasher for a short cycle, turn on each stove burner and the oven, and open the fridge to make sure it's cold. Try the garage door opener. Open and close windows and sliding doors. Check that you have keys, remotes, and gate or amenity cards if the community uses them.
Final Walk-Through Before Closing: What to Check in Myrtle Beach

Coastal Details Worth a Quick Look

Living near the ocean adds a few extra items to the list.

  • Fresh water stains on ceilings or around windows after recent rain
  • Standing water or new moisture in the crawl space if you can safely peek
  • Loose boards or railings on decks and outdoor stairs
  • Outdoor showers, irrigation, and hose bibs that run without leaking
  • Storm shutters or panels that were promised to convey

These take five minutes and can save you a headache in your first month.

Make Sure What Stays Is Still There

Your contract spells out what conveys with the home. That usually includes appliances, ceiling fans, light fixtures, and window treatments. Sometimes it includes furniture, a golf cart, or a TV mount. Confirm every item is still there and in working order. If a seller swapped out a light fixture you loved, that's a conversation to have before closing, not after.

What to Do If Something's Wrong

Stay calm. Most walk-through problems get solved quickly. Take photos and tell your agent right away. Small issues often get handled with a credit at closing. Bigger issues might mean the seller fixes them first, money gets held back at closing, or the closing date moves. Your closing attorney and both agents work that out together.

Let your lender know if anything serious comes up, since some loans have rules about the property's condition. Elite Home Lending works with buyers across the Grand Strand and can talk you through it at elitehl.com, and you'll find more on Myrtle Beach home loans on my site. Also double-check that your homeowners insurance is active starting on closing day.

After the Walk-Through Comes Closing

Once you sign off, you head to the closing table. If you want to know what happens there, read what actually happens on closing day in Myrtle Beach. And if you haven't seen your final numbers yet, this breakdown of closing costs in Myrtle Beach helps you know what to expect.

When you buy with me, Greg Harrelson, or one of my agents, we walk the house with you. We know what to look for, and we'll speak up if something isn't right.

Key Takeaways

  • The walk-through confirms condition, not a second inspection.
  • Go line by line through your repair addendum and ask for receipts.
  • Test every system, faucet, appliance, and door.
  • Look for new water stains and storm damage on coastal homes.
  • Confirm everything that conveys is still there.
  • Report problems to your agent before you sign at closing.

Frequently Asked Questions

When does the final walk-through happen?

Most happen within 24 to 48 hours before closing, sometimes the morning of. The timing gives the seller a chance to move out first. Your agent schedules it with the listing agent.

Can I skip the final walk-through?

You can, but I don't recommend it. Once you close, fixing a problem becomes your cost. Even a quick 20-minute visit protects you.

What if the seller hasn't moved out yet?

Tell your agent right away. The contract usually requires the home to be vacant and clean at closing unless you agreed otherwise. Your agent and the attorney can work out a fix, like a short delay or money held at closing.

Should the house be professionally cleaned?

Most contracts call for the home to be left in broom-clean condition. That means empty and swept, not deep cleaned. If you negotiated a professional cleaning, check that it happened.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Oct. 20, 2026

Should You Make Repairs Before Listing Your Myrtle Beach Home?

Fix the things that scare buyers. Skip the things buyers want to choose for themselves. That's the short answer, and it saves most sellers a lot of money and stress.

The longer answer depends on your home, your timeline, and your budget. Some repairs pay you back at the closing table. Others just eat your time and push your listing date back for no good reason.

Repairs That Usually Pay Off

Buyers forgive old paint. They don't forgive a roof leak. The repairs that matter most are the ones an inspector will flag and a lender or insurer might care about. Think roof leaks, active plumbing leaks, broken heating and air, electrical problems, rotted wood, and water damage. On the coast, add soft spots in decks and stairs, plus anything tied to moisture in the crawl space.

If a buyer finds these during inspection, they'll ask for a repair, a credit, or a lower price. Often the number they ask for is bigger than what the fix would have cost you up front. Fixing it before you list takes that leverage off the table.

Small Fixes With a Big First Impression

Some of the best money you'll spend is on cheap stuff. Buyers form an opinion in the first minute, and online photos shape that opinion before they ever walk in.

  • Fresh paint in neutral colors where walls are scuffed or bold
  • New caulk around tubs, sinks, and windows
  • Working light bulbs and switch covers that aren't cracked
  • Doors and cabinets that open and close without sticking
  • A clean, trimmed yard and a front door that looks cared for

None of that costs much. All of it tells a buyer the home was looked after. There's more on this in my guide on how to prepare your home for the Myrtle Beach market.

Upgrades You Can Usually Skip

A full kitchen remodel rarely pays for itself right before a sale. Neither does new flooring through the whole house, a bathroom gut job, or a pool. Buyers have their own taste. Many would rather buy the house at a fair price and pick their own countertops.

The exception is when your home is way behind the others in your neighborhood. If every comparable home has been updated and yours hasn't, we'll talk about whether a few targeted updates make sense. That's a pricing conversation, not a guess.

Should You Make Repairs Before Listing Your Myrtle Beach Home?

Should You Get a Pre-Listing Inspection?

A pre-listing inspection shows you what a buyer's inspector will likely find. You can fix the issues, get quotes, or price the home with them in mind. It also helps you fill out your disclosure accurately.

It's not right for every house. For a newer home in good shape, it may be overkill. For an older home, a rental, or a home you inherited and never lived in, it can save you from surprises halfway through the deal. If you'd rather offer a home warranty than fix every small item, look at how a home warranty compares to inspection repairs as a negotiation tool.

When Selling As-Is Makes More Sense

Sometimes the right move is to fix nothing. Maybe the home needs more work than you want to take on. Maybe you're out of state, or you need to move fast. That's okay. As-is homes sell here all the time when they're priced for their condition.

We also work with investors who buy homes in any condition when a seller needs to move quickly and can't wait on a traditional buyer. It's one more option to compare against a regular listing, and you get to decide which one fits.

Planning Your Next Move While You Sell

If you're buying your next home after this one sells, get your financing figured out before your listing goes live. Elite Home Lending helps Grand Strand buyers line that up, and you can reach them at elitehl.com or start with the home loan options for Myrtle Beach buyers on my site. Knowing your numbers early makes it easier to decide how much to spend on repairs now.

And if you're worried about getting stuck with an agent who doesn't follow through, our Easy Exit Listing Agreement lets you cancel anytime, hassle free. You're never locked in.

Not sure which repairs are worth it on your home? Ask me. I'm Greg Harrelson, and I'll walk through the house with you and give you a straight answer on what to fix and what to leave alone.

Key Takeaways

Fix problems that an inspector, lender, or insurer will flag, like leaks, rot, and broken systems. Spend a little on paint, caulk, and curb appeal, because those small fixes shape a buyer's first impression. Skip big remodels unless your home is far behind the neighborhood. If repairs aren't realistic, pricing as-is or selling to an investor can still get you a clean sale.

Frequently Asked Questions

Do I have to fix everything a buyer's inspector finds?

No. In South Carolina, repairs after inspection are a negotiation, not a requirement. You can fix items, offer a credit, adjust the price, or say no. Your agent helps you weigh each request against the risk of losing the buyer.

Is it better to offer a repair credit or make the repair myself?

It depends on the item and the buyer's lender. Credits are often simpler and let the buyer choose the contractor. Some loans, though, require certain repairs to be finished before closing.

Should I repair things I'm already disclosing?

Disclosing a problem protects you, but it doesn't make the problem go away. Buyers will still factor it into their offer. If the fix is cheap and clear, doing it before listing is usually worth it.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Sellers
Oct. 19, 2026

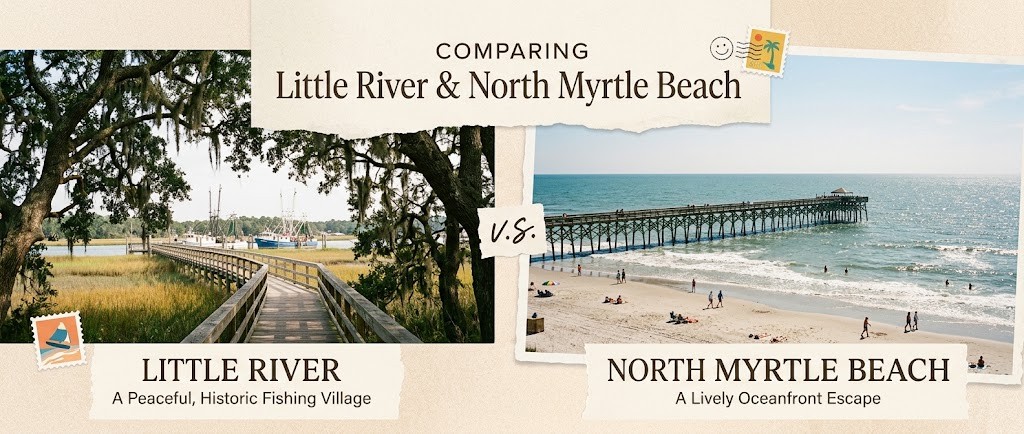
Comparing Little River and North Myrtle Beach

Little River and North Myrtle Beach Share a Border and Not Much Else

Buyers shopping the north end of the Grand Strand almost always weigh Little River against North Myrtle Beach. The two markets sit minutes apart, both touch the water, and both show up on the same MLS searches. Underneath that surface similarity, they behave as very different buying environments — different housing stock, different waterfront realities, different buyer profiles, and different pricing tendencies. Choosing between them is less about which is better and more about which fits how you actually want to live.

The Water Is Not the Same Water

North Myrtle Beach is an Atlantic Ocean town. The beach is the headline attraction, and the housing stock reflects it — oceanfront condos, ocean-block single-family homes, second-row cottages, and inland subdivisions oriented around pool-and-club amenity sets. Buyers come here because the beach is 90 seconds from the door.

Little River is an Intracoastal Waterway town. The water story runs through the ICW, the marina, and the creek-and-marsh system that feeds into Calabash and the North Carolina line. Boat owners settle here specifically because deep-water access, slips, and marina proximity cost less than they do farther south. Beach access still exists — Cherry Grove and the north end of North Myrtle Beach are a short drive — but the waterfront lifestyle in Little River is boat-first, not sand-first. Our overview of Little River homes for sale captures the current inventory.

Comparing Little River and North Myrtle Beach

Who Each Town Attracts

North Myrtle Beach draws snowbirds, second-home owners, vacation-rental investors, and full-time residents who want walkable beach-town energy. The identity leans tourist-friendly year-round, with a stronger shoulder-season rental economy than most of the Grand Strand.

Little River draws boaters, retirees who prefer a quieter rhythm, buyers looking for better square-foot value than oceanfront pricing allows, and families moving from pricier Carolina or Virginia markets. It tends to attract more full-time residents and fewer vacation-rental investors. For a fuller sense of who settles here, see our post on what buyers should know about living in Little River.

Housing Stock Comparisons

North Myrtle Beach is condo-heavy at the beach, single-family in the inland neighborhoods, and anchored by a handful of large resort communities led by Barefoot Resort. Price per square foot runs higher closer to the ocean and in gated-golf communities.

Little River leans single-family and townhome, with condo inventory concentrated along the ICW and near the marina. Tidewater Plantation, Coquina Harbour, and the mainland sections of Little River serve very different buyer profiles. The town has more inventory in the $300K to $600K band than oceanfront North Myrtle Beach, and that pricing gap is often the deciding factor for first-time full-time coastal residents. Our broader North Myrtle Beach real estate hub covers the comparison inventory.

Day-to-Day Rhythm

The two towns feel noticeably different on a Wednesday afternoon in July. North Myrtle Beach is active — traffic along Main Street, families walking to the beach, lines at restaurants, shag music drifting from Ocean Drive. Little River is quieter. Boats come and go from the marina, locals eat lunch at the ICW-side restaurants, and the pace resembles small-town Carolina more than a tourist destination. That difference is amplified in the shoulder season. Little River winter feels like winter in a small town. North Myrtle Beach winter still has activity.

Pricing and Days on Market

North Myrtle Beach pricing varies dramatically by section — oceanfront, ocean-block, and inland each have their own market. Well-prepared homes near the beach move quickly when priced to recent closed comps; overpriced listings sit regardless of location. Little River pricing is tighter across the town, with less dramatic variation between sections. Days on market in Little River run longer than oceanfront North Myrtle Beach but shorter than markets farther south like Pawleys.

Buyers should get pre-approved before writing offers in either market — our Myrtle Beach home loans page is the right starting point for coastal and second-home financing.

Taxes, Insurance, and Short-Term Rentals

Both towns sit in Horry County, so the primary-vs-non-primary tax ratio applies the same way. Insurance costs on coastal properties price similarly, though specific wind, hail, and flood exposure varies property to property. The bigger regulatory difference is short-term rental rules — North Myrtle Beach has established rental zones and infrastructure built around them, while Little River’s short-term rental market is thinner and more HOA-dependent. Investors should verify specific property rental rules before writing an offer in either market.

How to Decide

Beach-first buyers who want oceanfront or ocean-block proximity, a walkable beach-town rhythm, and an active year-round scene gravitate to North Myrtle Beach. Boat-first buyers who want better square-foot value, a quieter daily pace, and ICW or marina access gravitate to Little River. Buyers who want both lifestyles sometimes split the difference and settle in a Barefoot Resort section near the water or in Tidewater Plantation on the Little River side — both offer resort amenity sets with easy access to either town.

Key Takeaways

North Myrtle Beach is Atlantic Ocean, beach-town rhythm, year-round tourist energy, and condo-heavy coastal inventory. Little River is Intracoastal Waterway, boat-first, quieter rhythm, and single-family and townhome stock with better square-foot value than oceanfront pricing allows. Match the choice to the lifestyle you actually want, not just the one that photographs well.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Buyers
Oct. 18, 2026

Best Agent to Sell a Fixer Upper in Myrtle Beach

Selling a House That Needs Work Is a Buyer-Matching Problem

A fixer upper doesn't sell to the same buyer a move-in-ready house sells to. That's the whole game. The right agent knows which buyers can actually get a loan on a property in rough condition, knows what South Carolina still requires you to disclose even in an as-is sale, and knows which repairs raise your price and which ones just drain your savings. An agent who lists it like any other house and waits will watch it sit while the price bleeds down.

I'm Greg Harrelson, Broker/Owner of Century 21 The Harrelson Group in Myrtle Beach. Between my own transactions and the ones I've partnered on, that's 15,000+ homes and condos sold along this coast, and a good number of them needed work. You can read more about my background here. Below is how I think about a property that isn't pretty.

Why Financing Decides Who Can Buy Your Fixer Upper

Here's what nobody tells sellers. Your buyer pool isn't set by your price. It's set by your condition.

A conventional lender and its appraiser have opinions about the property, not just the buyer. FHA and VA loans come with minimum property requirements, and an appraiser working those files is looking for specific things. Peeling paint on a house built before 1978. A missing stair handrail. A roof near the end of its life. Exposed wiring. Heat that doesn't work. Any one of those can turn into a repair demand before the loan closes, and the seller usually gets asked to fix it.

So condition narrows the field. A house needing a new roof and a new HVAC system isn't competing for every buyer in Horry County. It's competing for three groups.

  • Cash buyers and investors, who don't answer to an appraiser's condition list.
  • Renovation-loan buyers using an FHA 203(k) or a Fannie Mae HomeStyle loan, which roll the repair budget into the mortgage.
  • Conventional buyers with enough cash on hand to handle the work after closing, on a house that still passes the appraisal.

Each group shops differently and pays differently. Marketing to all three the same way is how a fixer upper goes stale.

Do You Still Have to Disclose Problems in an As-Is Sale?

Yes. This trips up more sellers than anything else on this list.

The South Carolina Residential Property Condition Disclosure Act, Title 27, Chapter 50 of the state code, requires an owner of residential property to give the buyer a disclosure statement covering the condition of the home. The form comes from the state, and the Act spells out which transfers are exempt and how as-is agreements are treated. Selling as-is means you're not agreeing to make repairs. It does not mean you get to stay quiet about what you know.

If the house was built before 1978, federal law adds a lead-based paint disclosure on top of that.

Being straight about condition isn't a weakness in the marketing. It keeps a deal from dying in due diligence, and it keeps you out of a lawsuit after closing. To see what buyers and their inspectors actually find around here, I wrote up the common issues that show up during due diligence on Myrtle Beach coastal homes.

Which Repairs Are Worth Making and Which Ones Aren't

Sellers ask me this before anything else, and the answer isn't a list. It's a rule.

Fix what blocks a loan. Skip what only changes taste.

A dead HVAC, an active roof leak, rotten decking, a panel an inspector will flag, missing handrails, a crawl space holding water. Those shrink your buyer pool, so money spent there comes back. Kitchen cabinets, flooring, paint colors, a bathroom remodel. That's taste, and a renovation buyer will redo it anyway.

The exception is cheap and visible. Haul off the junk, cut the grass, trim the overgrowth, replace dead bulbs, and get real photographs taken. That costs very little and changes how every buyer reads the house. A rough property that looks cared for reads as a project. One that looks abandoned reads as a discount.

When a seller needs help lining up the work, our homeowner support services connect you with the local trades we use on our own listings.

The Coastal Carolina Problems That Show Up Here and Not Elsewhere

Salt air and humidity age a house faster on the Grand Strand than inland. A twenty-year-old home in Surfside Beach or Garden City Beach can have a corroded HVAC coil, soft exterior trim, and moisture under the crawl space that a similar home in Conway wouldn't.

Insurance is the other one. Wind and hail coverage near the water depends heavily on roof age and condition. A buyer who can't get an affordable policy can't close, no matter how much they like the house. On a fixer upper close to the ocean, the roof is often the single item standing between you and a deal.

Getting ahead of this beats reacting to it. I'd rather a seller hire a home inspector before we list than find out about the crawl space from the buyer's inspector on day eight of due diligence. You price the house knowing what it is, and nothing blows up mid-contract.

Should You Just Sell to an Investor?

Sometimes. It depends on what you're optimizing for.

An investor pays less and gives you speed and certainty. No appraisal, no repair requests, no loan falling apart two weeks in. If the property is badly distressed, or you need it gone by a date, that trade can be worth it.

What I won't do is send you straight to an investor without showing you the other number first. I keep relationships with investors who buy along this coast, so that option is there when you need it. But see what the open market would pay before you take a discount for speed. Plenty of sellers walk in assuming their house is too rough to list and find out it isn't.

What Should You Ask an Agent Before Listing a House That Needs Work?

  • Which of the three buyer groups is this house for, and how will you reach them?
  • What specifically will stop an FHA or VA appraisal on this property?
  • What are you going to tell me not to fix?
  • What does my net look like listed on the market versus sold to an investor?

An agent who can answer those four has sold properties like yours. An agent who starts with a list of renovations you should make before listing is about to spend your money. More seller questions get answered in our Myrtle Beach real estate FAQ.

Key Takeaways

Condition, not price, decides who can buy your fixer upper, so the job is matching the house to cash buyers, renovation-loan buyers, or conventional buyers with money set aside. Spend repair money only where it clears a loan hurdle, and leave the cosmetic work to whoever buys it. South Carolina still requires a property condition disclosure even when you sell as-is, so be straight about what you know. Along the Grand Strand, roof age and moisture carry extra weight because of insurance and salt air. And before you accept an investor's number, find out what the open market would have paid.

Frequently Asked Questions

Can I sell a house in South Carolina without making any repairs?

Yes. You can list and sell a property as-is, which means you are not agreeing to make repairs a buyer requests. You still have to complete the state property condition disclosure and answer honestly about what you know, and the buyer still gets to inspect during due diligence.

Will a buyer be able to get a mortgage on a fixer upper?

It depends on how rough the property is. FHA and VA loans carry minimum property requirements, so issues like a failing roof, no working heat, or exposed wiring can stop the loan. Renovation loans such as an FHA 203(k) or a Fannie Mae HomeStyle mortgage exist specifically to finance the purchase and the repairs together.

Should I get a home inspection before I list a fixer upper?

Usually yes. A pre-listing inspection tells you what the buyer is going to find, which lets you price the house accurately instead of renegotiating later. It also lets you fix the one or two items that would block financing and leave the rest alone.

How much less does a fixer upper sell for in Myrtle Beach?

There is no fixed discount. The gap depends on which repairs are needed, whether those repairs block financing, and how many similar properties are available at the time. The way to find out is a valuation based on what comparable homes in that condition have actually closed for nearby.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Sellers
Oct. 17, 2026

How Do I Choose an Agent to Sell My Aynor Home?

What to Look For in an Agent Before You List an Aynor Home

Hire the agent who has actually priced and sold property inland, not just along the ocean. The housing stock in Aynor runs from century-old farmhouses on several acres to brand-new builds in a subdivision, and whoever takes your listing has to value all of it. Ask what they have closed within fifteen miles of town, how they handle land assessed for agricultural use, and how they intend to reach a buyer who is not already driving around Horry County looking at farmland.

A seller off Highway 319 asked me point blank whether I had ever sold anything that was not within sight of the water. Fair question. The answer is a lot of them, and Aynor is one of the ten areas Zillow lists our team as serving. I am Greg Harrelson, and Century 21 The Harrelson Group is the company I own and run.

An Aynor Listing Is Not a Myrtle Beach Listing

Aynor is a farming town. The Census Bureau put the population at roughly 1,051 in 2023, and the beaches are about thirty miles east. Much of the land around town was tobacco, and plenty of the families who went on to build businesses in Myrtle Beach started on farms out here.

So the pricing problem is different. A condo on Ocean Boulevard has forty near-identical units to measure against. A brick ranch on nine acres between Aynor and Galivants Ferry has almost nothing that matches, and the few sales that do may be two years old and four miles apart.

Here's the thing most beach agents will not say out loud: that gap gets filled with a guess. Sometimes it is high and the home sits five months. Sometimes it is low and a seller hands over equity that was theirs to keep.

Think of a veterinarian who has spent fifteen years on indoor cats. Good at the job. Then somebody walks a horse into the parking lot. The training was not wrong. It was built for a different animal.

Acreage Changes How the Property Has to Be Valued

South Carolina lets qualifying farm and timber land be assessed on its agricultural use value instead of full market value, administered through the Horry County Assessor. When that land shifts to another use, rollback taxes can follow. An agent who does not know this will either ignore it or explain it wrong to a buyer, and both cost you.

Land also has to be separated from improvements. On a one-acre lot the house is the value. On fifteen acres with road frontage, the dirt may be worth more than the structure on it, and the buyer pool splits between those who want a home and those who want the tract. Our acreage and farmland pages exist because that is a distinct search, and Aynor property on an acre or more is one of the steadiest requests we get from inland buyers. If you think your assessed value is off, that is a separate conversation from list price, and our Horry County tax assessment page walks through the appeal.

No HOA Is a Selling Feature Out Here, and It Has to Be Marketed Like One

Aynor probably has more homes without a homeowners association than anywhere else in the county. For a buyer coming out of a coastal condo regime with monthly dues and a parking rule, that is the headline, not a footnote. Green Meadow Farms, out along Poplar Church Road where the Aynor and Conway lines meet, is custom homes on lots of roughly one and a half to six acres with no association fees. A listing that buries that detail in the twenty-eighth line of the remarks is wasting it. Space, a shop building, room for a boat, no board telling you where to park it — those are the reasons people drive inland, and they belong in the first photograph and the first sentence.

Ask How the Agent Plans to Find the Buyer

Nobody walks past an Aynor listing on the way to dinner. There is no foot traffic to inherit, so every buyer has to be gone out and found. That is the part I would press hardest on in a listing appointment.

In practice that means aggressive marketing built to put the property in front of qualified people rather than to look busy. Photography that shows the land, not just the kitchen. Video that gives a buyer three hundred miles away a reason to make the drive. Paid placement and social targeting aimed at the markets that actually relocate here.

For scale: our team has closed 16,377 sales, 903 of them in the last twelve months, per our Zillow profile as of October 2026. Volume alone does not sell your house. What it buys you is a database of buyers already in motion and a read on price that updates weekly rather than annually.

One Myrtle Beach seller said it plainly in a 2025 review: "She understands the market, and how to get a property sold."

Two Agents Worth Interviewing

Interview a small local shop alongside us. A one-agent office in Aynor or Conway gives you something a larger team has to work at: the person who sat at your kitchen table is the one who answers at nine on a Saturday night. Some sellers want that, and should have it.

Where we differ is reach. Eight Century 21 companies, eleven offices, two states, roughly 500 agents across that network — which matters when your buyer is in Charleston, Columbia, or Wilmington rather than Horry County. Ask us both the same questions and pick the answer you believe.

Key Takeaways

Choosing a listing agent in Aynor comes down to whether the person can value land, not just houses. Confirm they have closed inland recently, that they understand agricultural use assessment and rollback taxes, and that they can say how they will separate land value from the improvements on it. Make them show a marketing plan with dates, because an Aynor buyer has to be found rather than walked past. Treat the absence of an HOA and the size of the lot as lead selling points, not fine print. Then interview a small local office too and sign with whoever was specific.

Frequently Asked Questions

Does an agent need to live in Aynor to sell my home well?

No, but they need a closing history inland and a working knowledge of how Horry County treats farm and timber land. What matters is whether they have priced acreage before, not their mailing address.

How is an Aynor home with acreage priced when there are few comparable sales?

Land and improvements get valued separately, then combined. The house is measured against the closest inland sales available, and the acreage against land and tract sales, with adjustments for road frontage, tillable ground, timber, and whether the parcel can be divided. An agent who hands you one number without explaining how the land was treated has not done the work.

Should I appeal my Horry County assessment before I list?

Your assessed value and your list price are two different figures, and a high assessment does not raise what a buyer will pay. Appealing can lower your carrying cost while the home sits on the market, which is worth doing on its own merits. Keep the two decisions separate.

Is agricultural use assessment something a buyer takes over?

It depends on whether the buyer keeps the land in a qualifying use and files for it. If the use changes, rollback taxes can be charged on the difference. Raise it early, because it changes what a buyer can afford to pay, and have a real estate attorney confirm the particulars.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Sellers
Oct. 16, 2026

How to Sell an Annual Rental Property in Myrtle Beach

Selling an Annual Rental Starts With One Big Decision

You can sell an annual rental in Myrtle Beach with the tenant in place or deliver it vacant, and the right choice depends on three things: when the lease ends, what the rent looks like next to the market, and who is most likely to buy. The smartest first step is to map both paths before the sign goes in the yard. A rental isn't a normal listing, because someone lives there and that someone has rights.

Here's what I see on the Grand Strand. Owners often list a rental the same way they'd list a vacant home, then run into a tenant who doesn't want showings, a lease that scares off homeowner buyers, or investor buyers who want paperwork nobody gathered. All of that is fixable. It just needs a plan.

Selling With the Tenant in Place vs. Delivering the Home Vacant

When It Makes Sense to Sell With the Tenant In Place

If your tenant pays on time and the lease has months left, an investor buyer sees income from day one. That's a real selling point in areas like Little River, North Myrtle Beach, and Carolina Forest, where investors already shop. A signed lease at a fair rent turns your listing into a ready-made investment.

When Vacant Is the Better Move

If the lease ends soon and the buyer pool is mostly people who want to live in the home, vacant can bring a better price. A homeowner buyer wants to move in on their schedule, and a lease can stand in the way. Vacant also makes cleaning, painting, and photography simple. The trade-off is lost rent while the home sits, so we run the numbers both ways before you decide.

How to Sell an Annual Rental Property in Myrtle Beach

What South Carolina Law Means for Your Tenant During a Sale

Listing your rental doesn't end the lease. Under the South Carolina Residential Landlord and Tenant Act, the lease stays in force, and you need to give your tenant proper advance notice before you enter the home for showings or photos. The new owner steps into the lease, and your tenant's security deposit gets handled at closing.

That last part trips people up. Deposit records, lease terms, and any addenda need to be clean and complete. South Carolina closings go through an attorney, so connect with a Myrtle Beach real estate attorney early if your lease has anything unusual in it.

A little kindness goes a long way, too. A tenant who feels respected keeps the home clean and works with showing times. A tenant who feels ignored makes every showing harder. I talk with tenants directly, set a showing schedule that respects their routine, and keep them in the loop.

How Investor Buyers Look at Your Rental

An investor reads your listing like a balance sheet. They want to know the rent, the lease term, the payment history, and what it costs to carry the property. Non-owner-occupied property in South Carolina is taxed at the 6 percent assessment ratio, so the tax bill a buyer inherits can be higher than what a homeowner would pay. Insurance, HOA dues, and condo fees matter just as much.

Have these ready before you list:

  • Current lease and any addenda
  • Rent payment history
  • Security deposit amount
  • Recent tax and insurance bills
  • HOA or condo documents and rental rules

Buyers who can see the numbers make offers faster and with fewer questions. Many investors also need financing, so a lender like Elite Home Lending can tell them early what to expect. A local Myrtle Beach mortgage partner who understands investment property keeps that conversation simple.

Pricing and Marketing a Rental So It Sells

Pricing a rental means looking at it two ways: what a homeowner would pay, and what an investor would pay based on income. When those two numbers are far apart, that tells us which buyer to target. I pull recent closed sales and current rents, then show you both views side by side.

Marketing follows the buyer. For investors, we lead with the lease, the rent, and the carrying costs. For homeowners, we lead with the home itself. Greg Harrelson's team also keeps a network of investors for sellers who want a fast, clean sale, so your property can get in front of cash buyers early. Since 2006, Century 21 The Harrelson Group has sold 4,742 homes and 4,533 condos along the Grand Strand, according to CCMLS data, so we know what both kinds of rental actually sell for.

Taxes, 1031 Exchanges, and What Comes Next

Selling a rental can trigger a tax bill, and the right plan before you list can change the outcome. Some owners roll their proceeds into another investment property through a 1031 tax exchange, and your tax professional can tell you if that fits. If you want to keep the property but stop managing it, annual rental and property management is another route. I'd rather you know all your choices than sell because you felt stuck.

If you own a rental in Myrtle Beach, Surfside Beach, Conway, or anywhere along the Grand Strand, call me and we'll talk through the options.

Key Takeaways

  • Choose tenant-in-place or vacant based on lease end date and buyer type.
  • Listing a rental doesn't end the lease; proper notice is required.
  • Investors buy on numbers, so gather lease and cost records first.
  • Price a rental from both the homeowner and investor angles.
  • Talk to a tax professional about a 1031 exchange before you list.

Frequently Asked Questions

Can I sell my rental while a tenant is living in it?

Yes. The lease stays in effect, and the buyer takes over as the new landlord. You'll need to give your tenant proper notice before showings and keep your lease and deposit records in order.

Do I have to evict my tenant to sell?

No. Listing the property isn't a reason to end a lease early. If you want the home vacant, the cleanest route is usually to wait for the lease to end, or to talk with your tenant about a mutual agreement in writing.

What happens to the security deposit when I sell?

The deposit has to be accounted for at closing. Your closing attorney will handle the transfer or the credit to the new owner, so have your deposit record ready.

Will a tenant make my home harder to sell?

It can, if showings are hard to schedule or the home isn't kept up. It can also help, because a good tenant with a fair lease is attractive to investors. Communication with your tenant makes the biggest difference.

About Lance Molinaro

Lance Molinaro is a REALTOR® with Century 21 The Harrelson Group and a member of the Greg Harrelson Sales Team and Century 21 Collective. He serves sellers and buyers across the South Carolina Grand Strand and coastal North Carolina, from Myrtle Beach, North Myrtle Beach, and Surfside Beach to Conway, Little River, Pawleys Island, Georgetown, Oak Island, and Southport. His experience covers oceanfront condos, investment and resort properties, single-family homes, second homes, and relocation clients. Lance is known for transparent communication, data-driven pricing, and an actively managed marketing plan from first meeting to closing. Call or text him at (973) 665-4133 or visit his agent page.

Posted in For Sellers
Oct. 15, 2026

New and Upcoming Restaurants Along the Grand Strand (Fall 2026)

The Grand Strand Dining Scene Keeps Expanding

Fall 2026 is a strong moment for new restaurants across the Grand Strand. A handful of major concepts opened in the first half of the year, several more are slated to open before the holidays, and the balance between big-name entertainment-dining destinations and locally run neighborhood spots has rarely been better. Here is a current look at what is new, what is coming, and which neighborhoods are getting the most new food energy right now.

Opening dates and menus can shift. Verify hours directly with each restaurant before you drive. Where available, we have linked the official site or the roundup covering that spot.

Myrtle Beach — New Openings and What’s Still Coming

The biggest 2026 opening in Myrtle Beach real estate circles has been Guy Fieri’s Downtown Flavortown, a 50,000-square-foot restaurant and entertainment complex inside Myrtle Beach Mall at 10177 N. Kings Highway. It opened June 10, 2026, and pairs the restaurant with duckpin bowling, an arcade, and a tiki bar — a full evening on its own.

At Broadway at the Beach, Ole Smoky Distillery and Yee-Haw Brewing Co. opened a joint location May 20, 2026, featuring moonshine and whiskey flights, Yee-Haw craft beers, shareable food, and an outdoor beer garden overlooking the lake. Downtown, Big Dave’s Chews & Brews has filled the longtime home of Dagwood’s Deli and Bumstead’s Pub and runs late, with a kitchen open until 1 a.m. On South Kings Highway, Chocolate Bar & Grill opened this year with a brunch-forward menu.

In Carolina Forest, two newer additions anchor the area’s growing dining scene. SeaBasil Thai & Seafood had its grand opening on March 27, 2026 and quickly built word-of-mouth, and South Coast Beer Project — the first brewery in Carolina Forest — opened at 5020 Carolina Forest Blvd. with Detroit-style pizza, wings, and craft beer.

New and Upcoming Restaurants Along the Grand Strand (Fall 2026)

Big Fish at Broadway at the Beach is now open.  Still ahead in Myrtle Beach: The PicklePort on Harrelson Blvd. is targeting Q3–Q4 2026, and 357 Brewers in the Grande Dunes area was listed for spring 2026 and worth a current status check. Ocean Blue Prime Steak House is also coming to Market Common this fall as an upscale steakhouse addition. Broadway at the Beach also has a sizable 2027 addition on the way: the owners of The Grumpy Monk, Hop N’ Wich, The Sneaky Beagle, and South Coast Beer Project — operating as Coastal Concept Hospitality — are opening two new restaurants side by side, slated for mid-February 2027. Southern Social will be an elevated casual concept with composed dishes, a strong drink program, and late-night live music and karaoke. Rustic and Rye will sit next door as a walk-up, order-at-the-counter concept with table service. Both are coming to Broadway at the Beach, per reporting from The Myrtle Beach Sun News. For a complete current list, Visit Myrtle Beach keeps a running new restaurants roundup.

North Myrtle Beach — Coastal Seafood and Entertainment Dining

North Myrtle Beach has two openings that locals are watching closely. White Heron is an upscale coastal seafood concept at 1104 Hwy. 17 S., replacing the old Sea Merchants building, from the team behind Drift and Imperfecto Cantina — the official site now points to a later-2026 opening date. Alley Oops is a “Dine. Bowl. Play.” concept at 3607 Hwy. 17 S. that pairs full-service dining with bowling, arcade games, and VR experiences; originally slated for spring 2026, worth checking current status.

Up in Cherry Grove, The Grove House has opened this year and quickly became a go-to for North Strand regulars. For a running list of North Myrtle openings, the North Myrtle Beach Vacations roundup is updated regularly.

Murrells Inlet — Changes Coming to the MarshWalk

The pirate-themed Inlet Shipwreck Bar & Grill, which opened earlier in 2026 on Hwy. 17 Business, has already closed. The space is being reworked and will reopen as a second location for The Boathouse, the well-known waterfront restaurant and live-music venue. The MarshWalk itself is a reliably good night out year-round and will be especially packed for Grand Strand Witches’ Night on October 17 if you are planning to go that weekend.

Also in the Murrells Inlet area, Bohemian Bull Tavern is open at 2859 Hwy. 17 Business, bringing a casual pub-and-tavern vibe to the south-end dining mix.

Surfside Beach — Pier Dining and Neighborhood Spots

Since the Surfside Pier reopened in 2024, several pier-adjacent restaurants have anchored Surfside Beach real estate as a legitimate oceanfront dining destination. The Whistling Duck on the pier is a wine-bar-style spot with curated wines, craft cocktails, charcuterie, and small plates overlooking the ocean. Surf Diner, also on the pier, serves breakfast, seafood, burgers, and diner favorites with an oceanfront view.

Off the pier, Griffin’s Public House brings a casual pub feel to Surfside Drive, and Chico’s Chickens is drawing crowds for Latin-inspired charcoal rotisserie chicken with handmade tortillas. Milk & Honey Coffee Café started in Surfside and has now expanded to Forestbrook, worth knowing if coffee is part of the morning routine.

What This Means for the Grand Strand Dining Scene

Two patterns stand out across these openings. First, entertainment-dining is scaling — Flavortown, Alley Oops, and the Ole Smoky / Yee-Haw combo all pair food with activities. Second, the neighborhood-anchor approach is still working: Inlet Shipwreck, White Heron, SeaBasil, and the Surfside Pier restaurants are built on serving locals who come back week after week, not just tourists cycling through for a season.

For buyers evaluating neighborhoods, dining density is often an underrated signal. The parts of the Grand Strand getting the most new restaurants — Market Common, downtown Myrtle Beach, Carolina Forest, Cherry Grove, Murrells Inlet MarshWalk, and the Surfside Pier area — are also the areas with the most walkable neighborhood energy and strongest resale demand. Our overview of top Myrtle Beach neighborhoods matches the map pretty closely.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Oct. 14, 2026

Pawleys Island Lifestyle Guide for Remote Workers

Pawleys Island Rewards Remote Workers Who Want the Coast Without the Crowd

Pawleys Island has always been the quieter alternative to Myrtle Beach, and the rise of remote work has turned that identity into a serious draw. The pace here is deliberate. The beach is uncrowded most of the year. The restaurants know your name after a few visits. For the remote worker who wants coastal living without the tourist energy of the central Grand Strand, Pawleys delivers something you cannot find 20 miles north.

Here is what daily life actually looks like for a remote worker who settles in Pawleys, plus the practical considerations worth sorting before you make the move.

What the Day Actually Looks Like

Mornings in Pawleys start quiet. Beach walks on the island itself, coffee at one of the independent shops along Highway 17, and then back to a home office or a shared workspace before the first video call. The island’s rhythm invites a block-schedule approach to the day — deep work in the morning, a midday break for the beach or a kayak paddle in the creeks, and a second work block in the afternoon.

Evenings open up in a way they rarely do in a bigger city. Sunset at Pawleys Pier. Dinner at one of the long-standing local restaurants along Ocean Highway. A quiet drive home on roads that stay empty after dark. Remote workers who move to Pawleys consistently say the integration of work and daily life is the biggest shift — and the biggest win.

Pawleys Island Lifestyle Guide for Remote Workers

Internet, Cell, and the Technical Reality

The practical question most remote workers ask first is also the most important: does the internet work? The honest answer is yes, with caveats. Fiber service is available in most Pawleys Plantation, Litchfield, and Prince Creek-area communities, with reliable speeds for video calls, large file uploads, and multi-device households. Older homes closer to the island itself may still be on cable or DSL — verify specific service availability at the exact address before you buy. Cell signal on the island varies by carrier, and backup options like a mobile hotspot are worth keeping in the toolkit for storm season.

Co-working options exist in the Pawleys and Litchfield area, though they are smaller and less structured than what Myrtle Beach proper offers. Remote workers who need a dedicated office often convert a bonus room or an above-garage space in their home.

Where Remote Workers Actually Settle

Pawleys Plantation, Litchfield, Prince Creek, and the mainland neighborhoods along Highway 17 draw most of the remote-worker demand. The island itself is more vacation-rental heavy, and homes directly on the island are often second homes or multi-generational properties rather than full-time primary residences. Our overview of Pawleys Island real estate covers the current inventory, and the post on Pawleys Island neighborhoods with private, quiet settings walks through the sections best suited to work-from-home life.

Coffee Shops, Lunch Spots, and the Change-of-Scenery Problem

Remote workers who have done it for a few years know the home office goes stale fast. Pawleys has a solid rotation of coffee shops and casual lunch spots along Ocean Highway that work as a mid-day reset or an occasional change-of-scenery work session. The scene is smaller than Market Common or downtown Myrtle Beach but friendlier — by the third visit, you are a regular, not a tourist.

Weather, Hurricane Season, and Business Continuity

Hurricane season is a real factor. Remote workers depending on home internet should have a plan for extended power outages — a battery backup for the modem, a mobile hotspot, and an understanding employer are the usual elements. Most years this never matters. Occasionally it does. The homes with a whole-house generator and fiber service weather storms the best from a work-continuity standpoint.

Cost of Living Compared to Myrtle Beach

Pawleys trends higher on home prices and lower on everyday density than Myrtle Beach proper. Insurance costs are meaningful on coastal properties, and non-primary residence tax rates in Georgetown County are higher than primary rates. Buyers relocating from higher-cost metros usually find the overall cost of living favorable, but the specific insurance picture on a given property deserves a careful look. Buyers moving from the Northeast should read our full guide to what actually changes when moving to the Grand Strand.

Who Pawleys Works For and Who It Does Not

Pawleys works for remote workers who want quiet, who are comfortable driving 25 to 40 minutes for airport trips and larger shopping runs, who value a tight-knit community over a bigger night scene, and who have reliable work setups that do not depend on in-person networking. It works less well for people who thrive on urban energy, who need frequent in-person meetings in Myrtle Beach proper, or who want the broader restaurant and shopping variety of a bigger city. Deciding honestly which camp you fall into saves a lot of second-guessing after the move.

Key Takeaways

Pawleys Island works for remote workers who want a quieter coastal lifestyle, deliberate daily rhythm, and real community over tourist energy. Fiber internet is available in most mainland neighborhoods, with careful address-level verification worth doing before you buy. Pawleys Plantation, Litchfield, and Prince Creek draw most of the remote-worker demand, and hurricane-season business continuity planning is a real part of the picture. The lifestyle rewards people who match it; it frustrates people who expected a scaled-down Myrtle Beach.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Oct. 13, 2026

Georgetown Real Estate Market Overview

Georgetown Has Its Own Market, and It Behaves Nothing Like Myrtle Beach

Georgetown is the Grand Strand’s quiet southern anchor, and the local real estate market reflects that identity. It is slower, more deliberate, and built around a different buyer profile than the resort markets to the north. Days on market trend longer here. Inventory moves in smaller waves. Pricing conversations lean on history, charm, and waterway access more than on short-term rental math. For anyone evaluating a purchase or a sale in Georgetown, understanding how the market actually behaves is the difference between a smooth transaction and a frustrating one.

Market snapshot as of October 2026 — conditions can change and this piece will not be updated as they do.

Who Is Actually Buying in Georgetown

Georgetown draws a specific mix of buyers. Retirees looking for a slower-paced coastal town with real history. Full-time residents working at the Georgetown Hospital, the port, Georgetown County government, and remote jobs. Second-home owners who want a quieter alternative to Myrtle Beach. And a smaller but steady stream of buyers specifically targeting the historic district or the Winyah Bay and Sampit River waterfronts.

What you don’t see as much of here is the short-term rental investor crowd. Georgetown County short-term rental rules, limited inventory of rental-friendly properties, and the overall quieter rhythm of the town push most of that demand north to Pawleys Island and Litchfield. Local inventory on Georgetown real estate reflects that reality — most homes are being bought to be lived in, not rented out.

The Historic District

Georgetown’s historic district runs along Front Street and the surrounding blocks, with a stock of 18th- and 19th-century homes that are genuinely rare on this stretch of the Carolina coast. The market for these homes is thin by volume but consistent in demand. Buyers who want a historic home with real architectural character come to Georgetown first and often buy there.

The practical realities are worth knowing. Many of these homes carry higher maintenance costs because of their age, the materials, and the climate. Insurance can be complicated depending on wind, flood zone, and historic designation. Renovation decisions are often shaped by local historic preservation standards. Buyers who understand those tradeoffs tend to love the result. Buyers who assume a 200-year-old home will behave like a new build usually end up frustrated. For a deeper look at the historic district itself, see our post on Georgetown historic district homes and lifestyle. 

Georgetown Real Estate Market Overview

Waterfront, Marsh, and Winyah Bay Properties

Georgetown sits where five rivers meet the Atlantic at Winyah Bay, and the waterfront inventory reflects that geography. Marsh-front homes, deep-water lots with private docks, and bay-view properties all trade as distinct micro-markets within the overall Georgetown picture. Pricing on these homes is driven more by specific location, elevation, and dock access than by city-wide averages.

Flood zone, elevation certificate, and insurance quotes matter more on Georgetown waterfront than almost anywhere else on the Grand Strand. Buyers should get preliminary wind, hail, and flood insurance quotes before writing an offer, not after. The right property can be a lifetime home. The wrong property, with the wrong flood exposure and insurance picture, can be a decade of regret.

Days on Market and Pricing Realities

Days on market in Georgetown run longer than in Myrtle Beach or North Myrtle Beach, and that is normal. The buyer pool is smaller, and the right buyer for a specific historic home or waterfront property may need a few months to appear. Sellers who panic at 45 days on market and start reducing price often leave money on the table that a slightly more patient strategy would have captured.

Pricing honestly from day one matters more here than almost anywhere. Georgetown buyers are deliberate — they shop carefully, they wait for comps to close, and they know when a listing is overpriced. Zestimates and national algorithms miss this market by meaningful margins in both directions. A real local comparative market analysis is the only pricing method that works. For sellers, our free property valuation tool is a reasonable starting point before a full agent review.

Full-Time Resident Neighborhoods Outside the Historic Core

Beyond the historic district and the waterfront, Georgetown has a mix of full-time resident neighborhoods that work for families, retirees, and buyers wanting good value per square foot. These neighborhoods trade less often, which can make comp selection harder but tends to produce better long-term stability. Buyers moving to Georgetown from out of state should also read our overview of what actually changes when moving to the Grand Strand from the Northeast — the insurance, tax, and climate adjustments apply here too.

What Buyers Should Do in Georgetown This Fall

Buyers who are serious about Georgetown should get pre-approved with a lender who regularly writes coastal and historic-home loans, line up insurance quotes before writing offers, visit in person at least once to feel the pace of the town, and work with an agent who actually understands the historic district, the flood zone picture, and the waterfront micro-markets. Shortcutting any of these steps produces avoidable problems in a market that is otherwise one of the most rewarding on the Grand Strand.

What Sellers Should Do in Georgetown This Fall

Sellers should price against real local closed comps, prepare the home honestly for the inspection a careful buyer will order, be patient with days on market, and keep paperwork — historic designation documentation, flood certificates, dock permits, HOA records — organized and ready. Georgetown buyers reward sellers who respect the market’s pace. They punish ones who do not.

Key Takeaways

Georgetown is a slower, more deliberate market than the resort-driven stretches to the north, built around retirees, full-time residents, and historic-home buyers rather than short-term rental investors. The historic district and the waterfront around Winyah Bay are the two most distinctive sub-markets. Pricing honestly, planning for longer days on market, and front-loading insurance and flood zone research are how both buyers and sellers come out ahead here.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in Market Updates
Oct. 12, 2026

Second-Home Financing on the Grand Strand: What to Expect

Second-Home Loans Follow Their Own Rules

Financing a Myrtle Beach or Grand Strand second home is not a scaled-down version of a primary residence loan. Down payment expectations are different, interest rates price differently, insurance requirements are more involved, and lenders look at your file with different criteria. Buyers who assume their primary-home financing experience translates directly usually run into surprises.

Here is what to actually expect when you finance a second home on the Grand Strand, and where most buyers get tripped up.

What Counts as a Second Home?

Lenders draw a sharp line between three categories:

  • Primary residence — you live there most of the year
  • Second home — you use it personally, usually 14+ days a year, and it is not rented out full-time
  • Investment property — bought primarily for rental income, whether short-term or long-term

That distinction matters because rates, down payments, and reserve requirements shift meaningfully between the three. Lenders ask specific occupancy questions upfront — misrepresenting occupancy to get better terms is mortgage fraud, not a gray area.

Down Payment Expectations

Grand Strand second-home buyers should typically plan for:

  • 10 percent down as the practical minimum on most conforming second-home loans
  • 20 percent down to avoid mortgage insurance and get the sharpest rate
  • 25–30 percent down on non-warrantable condo buildings, which are common on the Grand Strand
  • Full-cash purchases if the property is in a building that cannot be financed at all (rare but possible on older oceanfront condos)

The condo down-payment reality is where most second-home buyers get surprised. Warrantability requirements have tightened, and buildings with high investor concentration, active litigation, or reserve shortfalls trigger higher down payment demands or outright loan denials.

Second-Home Financing on the Grand Strand: What to Expect

Interest Rate Expectations

Second-home rates usually run modestly higher than primary-residence rates, and investment-property rates are higher still. Exact spreads change with the market, but budget as if your second-home rate will not be identical to what your neighbor got on their primary. Start rate discussions with a lender who regularly writes coastal second-home loans — see our Myrtle Beach home loans page for local relationships.

Documentation and Reserves

Underwriters on second-home files typically want:

  • Two years of tax returns, W-2s, and recent pay stubs
  • Two months of bank statements documenting the down payment source
  • Proof of reserves — usually two to six months of PITI (principal, interest, taxes, insurance) on both the primary and the new second home, in liquid accounts
  • Documentation on your existing primary home's equity, taxes, and insurance
  • Clean explanation for any large deposits or transfers

Reserves are the piece buyers routinely underestimate. Having the down payment is not the same as having the reserves. Lenders want to see you can carry both properties if income disruption occurs.

Coastal Insurance Realities

This is where Grand Strand second-home financing separates from second homes in inland markets. Lenders require:

  • Homeowner's policy with wind and hail coverage, priced meaningfully higher on coastal properties
  • Flood insurance if the property is in a designated flood zone (many are, especially in Garden City, Cherry Grove, and low-lying Myrtle Beach neighborhoods)
  • Sufficient coverage limits to satisfy the lender's replacement-cost requirements

Buyers should get preliminary insurance quotes before writing an offer, not after. Insurance carriers have repriced coastal risk substantially in the last few years, and the annual premium can shift the deal math.

Rental Income and Second-Home Classification

Buyers who plan to rent the property occasionally have to be careful. On a true second-home loan:

  • Limited personal use plus occasional rental is generally acceptable
  • Renting the property year-round with only rare personal use crosses into investment-property territory
  • Lenders can and do audit occupancy after closing on second-home loans

If the plan is meaningful short-term rental income, structure the loan as an investment property from the start. The rate and down payment will be higher, but the loan will match reality. Our overview of what buyers should know before purchasing in Myrtle Beach covers the wider decision.

Property Tax Considerations

South Carolina taxes non-primary-residence properties at the 6 percent assessment ratio instead of the 4 percent primary-residence ratio. On a $500,000 Grand Strand second home, that difference is a meaningful annual line item. Buyers relocating from higher-tax states sometimes assume Horry County taxes are trivial and are surprised on the closing statement.

Timeline for a Second-Home Purchase

A well-run second-home purchase from offer to close usually runs 30 to 45 days. It runs longer when:

  • Insurance binder takes extra time because of flood zone or building specifics
  • Condo warrantability review turns up issues
  • Buyer's primary income requires additional verification
  • Appraisal is contested or comes in below contract price

Buyers relocating between homes should also read our post on moving to Myrtle Beach from the Northeast and your first 30 days after closing on a Grand Strand home.

Frequently Asked Questions

Can I use a second-home loan on a condo I plan to rent short-term?

Usually no. If short-term rental is the main use, lenders classify the loan as an investment-property mortgage, which carries a higher rate and higher down payment. Limited personal use plus occasional rental to friends and family is sometimes acceptable on a second-home loan — clarify with your lender before writing the offer.

What down payment should I plan for on a Grand Strand condo second home?

20 percent is a safe planning number for most warrantable buildings. Non-warrantable condos, which are common on the Grand Strand, may require 25 to 30 percent. Confirm the specific building's warrantability with your lender before making an offer.

Do I need a South Carolina address to get a second-home loan here?

No. Second-home loans are specifically designed for buyers whose primary address is elsewhere. The lender simply verifies where you actually live and treats the Grand Strand purchase as a second home based on your occupancy statement and use pattern.

How much should I budget for coastal insurance on a Myrtle Beach second home?

Highly property-specific. Elevation, flood zone, age, distance from the ocean, and building materials all shape the premium. Get a preliminary quote from a Grand Strand insurance broker before you finalize your budget — do not use a national estimator.

Key Takeaways

  • Second-home loans price differently than primary-residence loans — rates, down payments, and reserves all shift
  • Plan for 10 to 20 percent down on standard second homes, higher on non-warrantable condos
  • Lenders want two to six months of reserves in liquid accounts on both properties
  • Get coastal insurance quotes before writing the offer, not after
  • Do not misrepresent occupancy to get better financing terms — it is mortgage fraud
  • Non-primary property taxes in Horry County use the 6 percent ratio, meaningfully higher than primary

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers