Okay, let's talk about the part nobody puts in the listing photos. Your mortgage is only one line in the cost of owning a home in Myrtle Beach. On top of principal and interest, you'll carry property taxes, homeowners insurance, possibly wind and flood coverage, HOA or condo fees, utilities, and upkeep. No single number fits every buyer. The total depends on the property type, the location, and whether the home is your primary residence.
And here's the fun part. (Yes, I said fun!) You can learn the real cost of a specific property before you make an offer. I've lived on the Grand Strand since 2005, and I've seen two Myrtle Beach real estate listings at the same price turn into totally different ownership experiences. The difference almost never shows up in the photos. So let's go find it together.
Why Do Property Taxes Depend on How You Use the Home?
This one makes people say, "Wait, what?" South Carolina assesses a primary residence at 4%. A second home or rental is assessed at 6%. Same house, same street, very different tax bill. To get the lower rate, you have to apply for the legal residence exemption through the county. In Horry County, that runs through the Assessor's Office. It isn't automatic, and a buyer who skips the application can end up paying the higher rate without even knowing it. Nobody wants that surprise.
Quick heads up: the seller's current tax bill is not a preview of yours. A sale can trigger a reassessment, and the seller may have had a different rate or exemption than you will. Millage rates also vary by tax district, so two addresses in the same county can land on different bills. If you're 65 or older, ask whether you may qualify for the South Carolina Homestead Exemption. Buying in Georgetown County? Confirm that county's process the same way.
How Does Coastal Insurance Change the Numbers?
Insurance is the one that surprises buyers most, and I totally get it. A standard homeowners policy is only the start. Along the coast, you may also see a separate wind and hail deductible, which is often a percentage of the home's insured value instead of a flat dollar amount. If the home sits in a flood zone, flood coverage joins the party. Roof age, year built, elevation, and distance from the water all affect both the price and the availability of coverage.
Condos work differently. The association carries a master policy on the building, and you carry your own policy for the interior. What the master policy covers, and what it leaves to you, changes your cost. Get a quote from a local professional before you commit. Our Myrtle Beach homeowners insurance page is a great place to start. I'd much rather you see the premium during your due diligence period than at the closing table. Closing day should be for celebrating!
What Do HOA and Condo Fees Actually Cover?
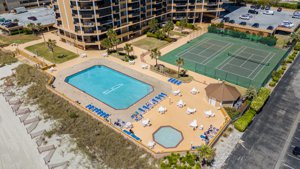 A monthly fee tells you almost nothing on its own. What matters is what it pays for and whether it's enough. Some fees include exterior maintenance, building insurance, water, trash, pools, and landscaping. Others cover little more than the common areas.
Why Reserves and Special Assessments Matter
A low fee can look like a bargain, but it can be a red flag. If an association isn't setting aside enough money for roofs, paint, elevators, and pavement, owners can face a special assessment later. That bill lands on you, often with little notice. It's also one reason some lenders look closely at certain buildings.
Why Rental Rules Change the Value
If you're buying a second home or plan to rent, the rules decide whether your plan works. Minimum stays, rental caps, and fees differ from building to building, even inside the same resort area. If you're comparing Myrtle Beach condos for sale, or looking at a resort-style community like Barefoot Resort condos, read the rules for the exact building you're considering. Before you offer, or as soon as your contract allows, ask for these items:
- The current annual budget and last year's financials
- The reserve study or reserve balance
- A summary of the master insurance policy
- The governing documents and rental rules
- Recent meeting minutes, including any talk of assessments or litigation
I know, reading HOA documents isn't exactly a beach day. But it's some of the cheapest protection you'll ever buy. A Myrtle Beach real estate attorney can help you understand what they mean for your situation.
What Should You Budget for Maintenance, Utilities, and Salt Air?
Coastal homes work hard. Humidity keeps your air conditioning running for months. Salt air and sun wear on exterior paint, decks, railings, windows, and outdoor units. Roofs take wind and heavy rain. An aging HVAC system or roof can turn into a major expense, and summer utility bills run higher than many out-of-state buyers expect. (I've seen a few jaws drop!)
Property type changes the kind of work you take on. A condo may reduce day-to-day maintenance, but it adds documents to review and shared costs you don't control. A single-family home gives you more freedom, and it also gives you every repair. If this will be a second home, think about who  checks on it while you're away. My cat Milo is a wonderful squirrel watcher, but he's not much help with a leaky faucet.
A good inspection helps you separate routine upkeep from near-term expenses. Hire someone who knows coastal systems. Our Myrtle Beach home inspector page can point you in the right direction.
How Does Your Loan Fit Into the Total Cost of Ownership?
Your lender sees many of these costs before you do. Taxes, insurance, and HOA dues all count toward your monthly obligation when a lender decides what you can borrow. That's why I love for buyers to talk with a lender early, before they fall head over heels for a listing.
Elite Home Lending is a Myrtle Beach mortgage company with an education-first approach, and loan officer Travis Buis is licensed across South Carolina. On its website, Elite Home Lending explains that many Myrtle Beach condo buildings aren't warrantable, which can limit financing options, and that wind and hail deductibles and flood zones can change what you qualify for. Those are exactly the details I want you to know before you write an offer. Already have a quote from another lender? Elite Home Lending also offers a second look at it.
How Can You Compare Two Properties Fairly?
Don't compare price alone. Compare the full cost of owning each one. Picture a condo with a higher monthly fee that includes exterior insurance and maintenance. Now picture a single-family home with no HOA, where you pay for your own roof, windows, wind deductible, and lawn. Neither one is better. They're just different ways to live.
The most useful question is what you value most: time, flexibility, or control. Once you know that, the right cost structure gets much easier to see. Figure that out first, and the numbers start working for you instead of surprising you.
“Considering a home in Myrtle Beach? Send me the listing, and I’ll help you identify the ownership costs and property-specific questions to investigate before you make an offer.”
Call or text me at 843-429-1578, or email lmendieta@c21harrelson.com. I love talking real estate (just ask anyone who knows me.), so don't be shy.
Key Takeaways
- Your mortgage is one piece of the cost of owning in Myrtle Beach.
- Primary residences are assessed at 4%, second homes and rentals at 6%.
- Check wind, hail, and flood coverage before you make an offer.
- Read HOA budgets, reserves, and rental rules, not just the monthly fee.
- Talk with a lender early so insurance and dues are in your numbers.
Frequently Asked Questions
How much are property taxes on a home in Myrtle Beach?
It depends on the purchase price, the tax district, and how you use the home. South Carolina assesses a primary residence at 4% and a second home or rental at 6%. Ask for an estimate based on your own purchase price instead of relying on the seller's bill.
Do I need flood insurance for a Myrtle Beach home?
If the home is in a high-risk flood zone and you have a federally backed loan, your lender will likely require it. Even when it isn't required, it's worth getting a quote. Flood damage is usually not covered by a standard homeowners policy.
Why do HOA fees vary so much between buildings?
Each association decides what its fee covers. One may include exterior insurance, water, and maintenance, while another covers only common areas. Always compare what the fee pays for, plus the reserve funding behind it.
Is a condo cheaper to own than a single-family home in Myrtle Beach?
Not always. A condo can reduce maintenance, but monthly dues, assessments, and insurance structure all add cost. The better choice depends on the specific property and how you plan to use it.
When should I look at ownership costs?
Before you make an offer. Once you know the taxes, insurance, and association costs, you can decide with the full picture. Send me the listing and I'll help you find the right questions to ask.
This post is for general educational purposes only and is not tax, legal, insurance, or lending advice. Tax rules, insurance premiums, exemptions, and fees change and vary by property and individual circumstances. Please consult qualified professionals before making a decision. Elite Home Lending, LLC, NMLS #2788023. All loans are subject to credit and property approval.
About Lori Lee Mendieta
 Lori Lee Mendieta is a REALTOR® with Century 21 The Harrelson Group in Myrtle Beach, SC, serving buyers across the Grand Strand. She has lived on the Grand Strand since 2005 and spent 25 years in the world of sports before bringing that same preparation, strategy, and competitive spirit to real estate. Clients know her for her big smile, her laugh, and her love of a good conversation. Lori Lee loves educating buyers, including first-time buyers, investors in commercial properties, and those using FHA, USDA, or VA loans. Her approach is simple: protect your investment, bring clarity to every step, and help you move forward with confidence. Reach her at 843-429-1578, lmendieta@c21harrelson.com.